If you have been putting off buying a home because you are waiting for the perfect mortgage rate, you are not alone. It is one of the most common things I hear from buyers across Welland and Niagara: "I will buy as soon as rates drop a little more." Here is the message that matters right now: the mortgage market continues to shift, and in a market that is moving quickly, waiting for the perfect rate can actually cost you. Let me explain in plain English, with no jargon and no crystal ball.
What's Happening with Rates
You do not need to follow the financial news to get the important part. Here is what is happening, in simple terms:
- Fixed rates are under pressure. Higher oil prices, fresh inflation concerns, and elevated bond yields are pushing lenders' costs up, and lenders build those costs into the fixed rates they offer you.
- Expectations for the Bank of Canada have shifted higher. That does not mean a hike is guaranteed tomorrow. It means the bar for future cuts has moved, and the direction of travel is cautious.
- Nobody can promise you what rates will do next. What we can see clearly is that the pressure is pointing one way for now, and waiting on a guess is a risky game with your home budget.
Why the 'Perfect Rate' Is a Trap
Here is the problem with waiting for the perfect rate: in a moving market, the perfect rate might not exist. It is a number we invent in our heads to feel safe, but the market does not wait for it. While you wait for that imaginary number, today's real rate can quietly slip away as lenders adjust to higher costs.
The practical move is simpler than it sounds: get pre-approved and lock in what is available now. A pre-approval holds today's rate for you while you search for the right home. You stop watching the news with anxiety and start shopping with confidence. If rates later move your way, you can always refinance. If they move against you, you are already protected. Either way, you win.
What This Means for Welland Buyers
Affordability matters more than the last decimal point on a rate, and that is where Welland shines. Welland is one of Niagara's most budget-friendly markets, a place where today's rate plus today's price can still stretch your dollars surprisingly far. The math that feels stretched in Toronto or even Hamilton often works comfortably here.
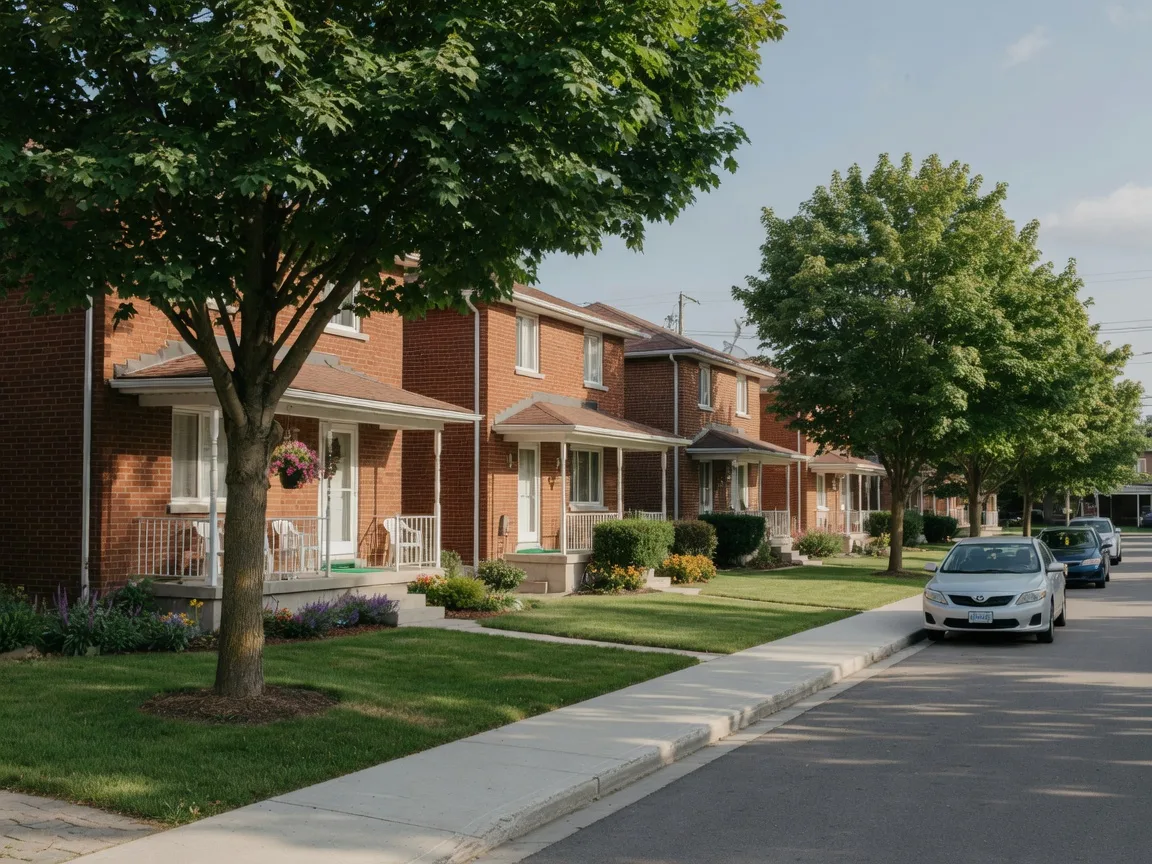
Quiet, well-kept streets like this are part of what makes Welland one of Niagara's most budget-friendly markets.
A home like 42 Terrace Avenue shows the value that is out there right now. It is a 4-level semi-detached backsplit with 3+1 bedrooms, two kitchens, and a separate entrance to the lower level, with multiple living areas across the levels. Outside, a 30x110 foot lot with no rear neighbours gives you a private backyard, and the home is carpet-free with fresh paint and new laminate flooring on the main and upper levels. Close to parks, trails, schools, and the Welland Recreational Waterway, it is the kind of home that makes today's rate feel like a good deal, not a compromise.
Get Pre-Approved in Plain Language
I work closely with the M2 Mortgage Team, and they explain mortgages in plain language, no jargon and no pressure. They can help you get pre-approved and lock in a rate that works for today's market. Start with them at m2mortgageteam.ca, or reach out to me first and I will make the introduction.
Talk to M2 Mortgage TeamFrequently Asked Questions
Are rates going to keep going up?
No one can promise the future. What we can say is that fixed mortgage rates are under pressure from higher oil prices, inflation concerns, and elevated bond yields, and expectations for the Bank of Canada have shifted higher. That is exactly why locking in today's rate now protects you if rates rise. If rates stay flat, you lose nothing.
What's a bond yield?
Think of it as the interest rate investors get for lending money to the government. When bond yields go up, lenders' costs go up, and fixed mortgage rates usually follow. It is one of the biggest hidden levers behind the rate you are quoted.
Should I wait to buy?
Waiting can cost you twice: today's rate can quietly slip away, and home prices in an affordable market like Welland can firm up while you wait. If you are financially ready, the stronger move is usually to get pre-approved and buy when the right home shows up, not to wait for a perfect moment that may never come.
How do I lock in a rate?
You lock a rate through a pre-approval or rate hold with a lender or mortgage broker. Your lender guarantees today's rate for a set period, usually 90 to 120 days, while you finish your search. The team at M2 Mortgage can do this for you in plain language.
How long does pre-approval take?
Usually a few days. You share basic documents like income, assets, and down payment, your lender checks the numbers, and you get a letter confirming what you qualify for and the rate you are locking in. It is free, and it turns your search from guesswork into confidence.
Don't Wait for Perfect. Book a Call and See.
The best rate is the one you actually lock in. Book a viewing of 42 Terrace Avenue or a planning call, or text me anytime. Let's talk through your numbers together, in plain English.